Insurance guides by industry
The questions particular to restaurants, contractors, salons, auto shops, retail and firms.
15 articles
Newest first
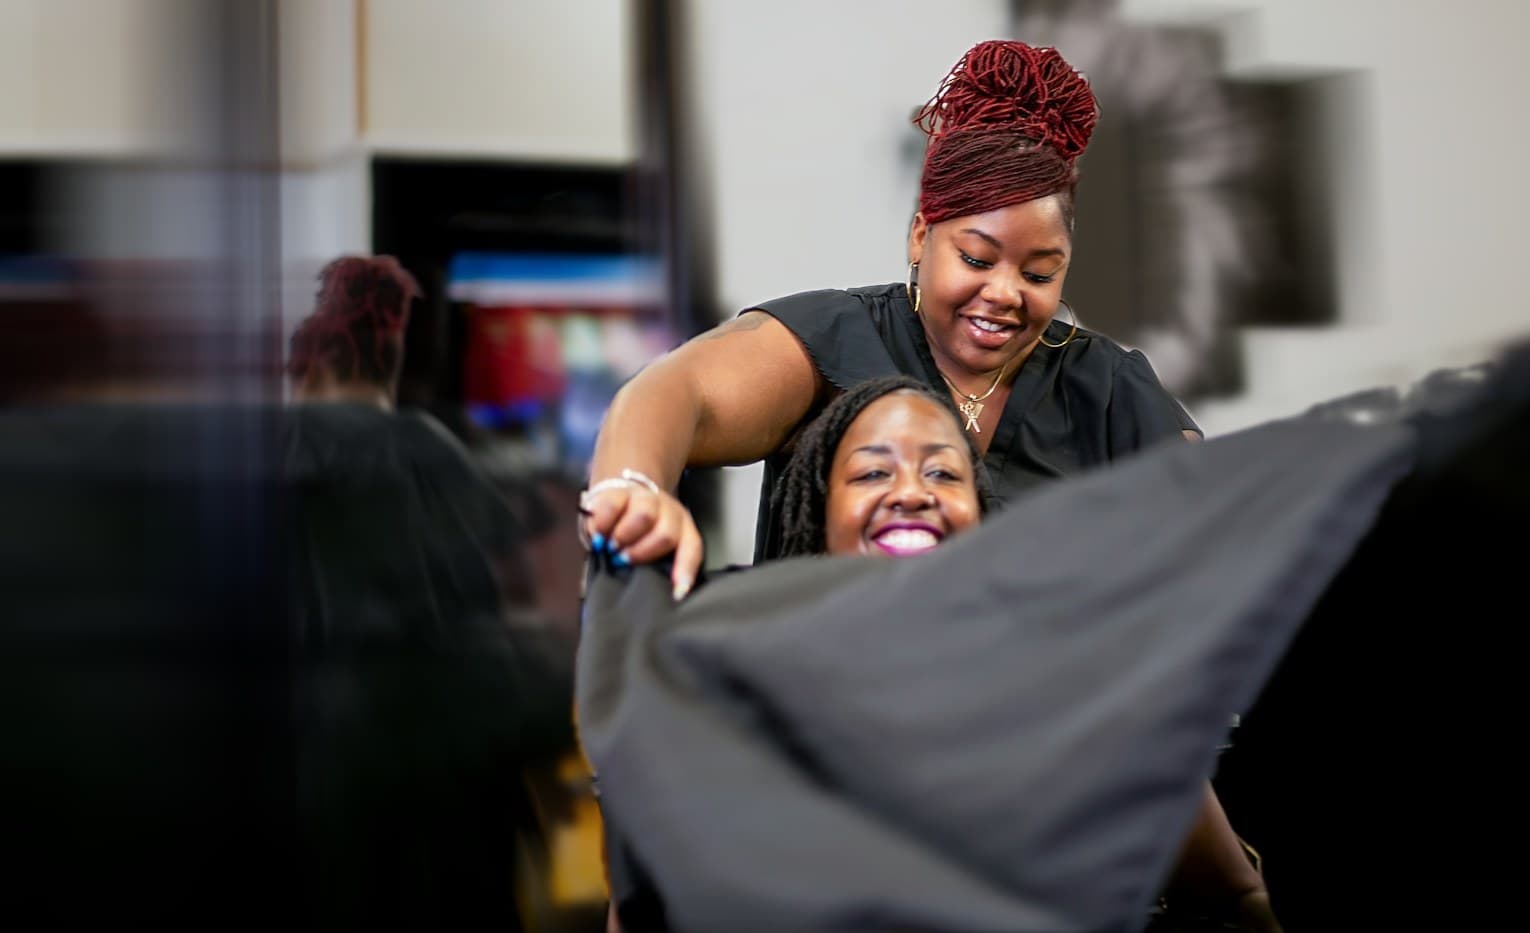
Barbershop insurance: chairs, clippers and the people in them
General liability covers the client who slips on hair clippings. Professional liability covers the razor nick that gets infected or the relaxer that burns. Add property coverage for the chairs and workers’ comp for barbers on your payroll, and require chair renters to carry their own.
Industry guides8 min read
Cleaning business insurance: what house and office cleaners need
Start with general liability, because broken things and wet-floor falls are the claims cleaners actually face. Add workers’ comp when anyone else cleans for you, cover the equipment you haul, and know that theft by a cleaner needs a bond, which is a different product.
Industry guides9 min read
Errors and omissions insurance for real estate agents
Errors and omissions insurance, the real estate version of professional liability, covers claims that your mistake or oversight cost a buyer or seller money. A brokerage policy usually covers you only while you’re with that brokerage, and a few states, including Colorado and Tennessee, make E&O a condition of the license.
Industry guides8 min read
Food truck insurance: what you need before your first event
You’re insuring two things: a kitchen, which needs general liability and coverage for its equipment, and a vehicle, which needs commercial auto, a separate policy. Many events will also want a certificate naming them before you can park.
Industry guides9 min read
Handyman insurance: what you need for small jobs
The usual starting point is general liability for damage in clients’ homes and tools and equipment coverage for what rides in the van, then add workers’ comp once they pay a helper. Small jobs can still produce large claims, and state licensing rules can cap the work you take on.
Industry guides8 min read
Landscaping business insurance: mowers, crews and flying rocks
General liability for the rock your mower throws through a window, tools and equipment coverage for the mowers and trimmers on your trailer, and workers’ comp once you have a crew. If you spray anything, check your pesticide license and your policy’s pollution exclusion before the season starts.
Industry guides8 min read
Personal trainer insurance: clients, gyms and online coaching
The claim that matters most is a client who gets hurt doing the exercise you prescribed, and that usually belongs to professional liability. Add general liability for accidents, and expect any gym or studio you rent space from to ask for a certificate naming them.
Industry guides7 min readPhotographer insurance: gear, venues and unhappy clients
Cover the camera bag with tools and equipment insurance, carry general liability because venues will ask for it, and add professional liability for the claim that hurts most, a client who says you missed the shots or lost the files.
Industry guides8 min readPlumber insurance: leaks after you leave and what covers them
When a fitting you installed fails weeks later, general liability’s completed operations coverage typically pays for the water damage, subject to its terms. It usually won’t pay to redo your own work, and it only helps if your policy is in force when the damage happens.
Industry guides7 min read
Booth renters vs. employees: insurance for salons
If your stylists are employees, your salon’s policies cover their work and their injuries. If they rent booths, each one is usually a separate business that needs its own general and professional liability, and you insure the space, the shared areas and your own staff.
Industry guides9 min readDo consultants need professional liability insurance?
Most do. If clients act on your advice or rely on your deliverables, professional liability is the policy that typically responds when they say your work cost them money, and many client contracts require it before you start.
Industry guides8 min readOpening a restaurant: an insurance timeline
Your insurance usually has to start when you get the keys, often months before you open the doors. Here’s what to have in place at each step, and who will ask to see it.
Industry guides10 min readShoplifting, break-ins and employee theft: what insurance covers
A break-in is usually covered by your property insurance, subject to its terms and deductible. Shoplifting and unexplained inventory shortages often aren’t, and theft by your own employees typically needs separate crime coverage.
Industry guides9 min readWhat insurance contractors need to win jobs
Most jobs ask for general liability that covers completed work, workers’ comp or a state exemption, and endorsements like additional insured and waiver of subrogation. Here’s how to read the request and get proof out fast.
Industry guides10 min read
Who pays when a customer’s car is damaged at your shop?
Usually your garagekeepers coverage, if the car was in your care and the cause is covered. Whether you bought legal liability or direct coverage decides what happens when the damage isn’t your fault.
Industry guides9 min read
Read enough? See your price.
A quote takes about five minutes, and your certificate is ready the day you buy.