Insurance for auto repair shops
General liability usually excludes the most valuable thing in your shop: the customer’s car. Most shops carry garagekeepers for that, plus general liability, tools coverage and workers’ comp.
- Usually starts with
- Garagekeepers and general liability
- Often asked for by
- Landlords and fleet customers
About five minutes. Your certificate is ready the day you buy.
What goes wrong in a garage
What happens most often to auto shops, and the policy that answers each one.
- Garagekeepers
01
A car comes off the lift
An arm slips, and a customer’s SUV drops onto the bay floor. Garagekeepers can help pay to repair the customer’s car, which general liability usually excludes.
- Garagekeepers
02
Hail on the overnight lot
A storm dents every car waiting for parts. Legal liability coverage pays only when you’re at fault, so storm damage usually needs garagekeepers with direct coverage.
- General liability
03
A customer slips in the bay
A customer walks back to look at their car and slips on spilled coolant. General liability typically covers their medical bills and your defense.
- Workers’ comp
04
A mechanic hurt under a car
A jack stand shifts, or hot coolant sprays from an open radiator. Workers’ comp pays for treatment and part of the mechanic’s wages while they recover, as your state’s rules set out.
- Tools and equipment
05
The scan tool walks out
A break-in takes the diagnostic scanner, the impact guns and a rolling chest. Tools and equipment coverage can help pay to replace them, subject to its terms and deductible.
The coverage auto shops carry
In the order most owners buy it. Quote them together and see every limit before you pay.
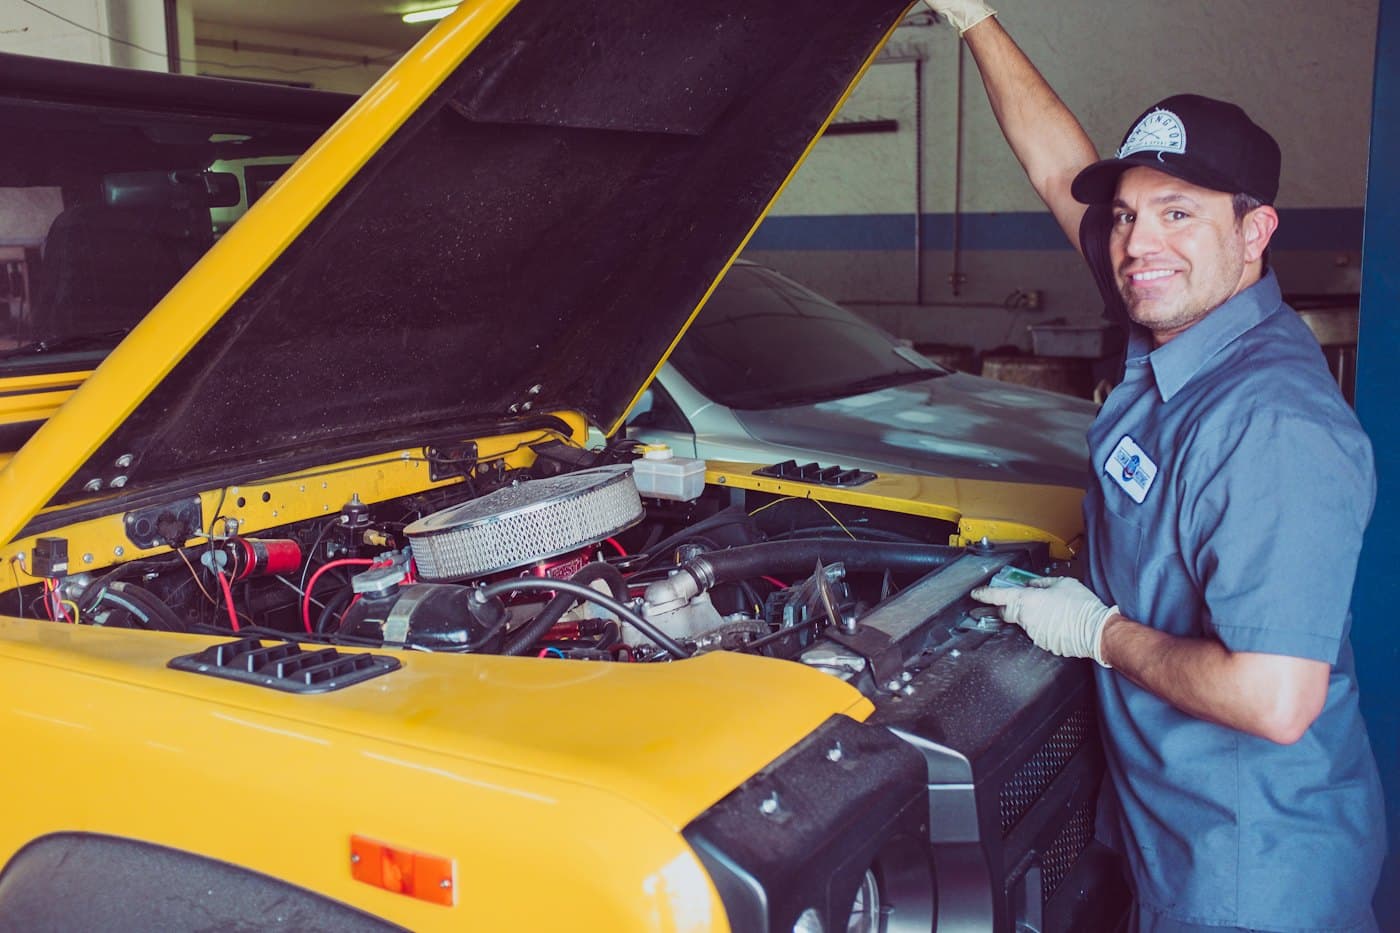
Numbers on the photo match the policies beside it.
- Most carry it01 Garagekeepers
Customers’ cars in the bay, on the lot and on test drives. General liability usually excludes property in your care, so this fills the gap.
Up to $100K - Most carry it02 General liability
For customers hurt at your shop, and damage your work causes to other people’s property.
$1M / $2M - Most carry it03 Tools and equipment
Lifts, jacks, scanners and air tools, often worth more than anything else you own.
Up to $50K - Once you hire04 Workers’ comp
Shop work is physical, and most states require it once you have employees. Rules vary by state.
Set by state - Often added05 Property
Your parts stock, office, waiting room and anything you built out in the space.
What you own
Who will ask for proof
Your certificate is ready the day you buy, so you can send it as soon as someone asks.
Landlords
Usually general liability with the landlord named as an additional insured, and sometimes a waiver of subrogation. Leases for shop space often set their own limits.
Fleet customers
Businesses that send their vans to you often ask for proof of garagekeepers and general liability before they sign a service agreement.
Equipment lenders
If you financed a lift or an alignment rack, the lender usually asks to be listed as a loss payee on the policy that covers it.
Franchisors
Franchise shops usually have to meet minimum limits for each policy set in the franchise agreement.
What moves your price
There’s no price on this page. Your quote is the real number, in about five minutes.
How much does business insurance cost?- 01How many cars you hold, and what they’re worth
- 02The work you do: repair, body work or detailing
- 03Indoor storage, fencing, lighting and key control
- 04Legal liability or direct coverage
- 05The value of your lifts and tools
- 06Your claims history
Keep claims small
Habits that make a claim less likely, and easier to settle when one happens.
Inspect lifts on a schedule
Have lifts inspected regularly and keep the records. Check that the arm locks engage every time.
Lock down keys and the lot
Keep customers’ keys in a locked box, light and fence the lot, and bring cars inside overnight when you can.
Photograph cars at drop-off
A few photos of each panel at check-in show what damage was already there.
Set rules for test drives
Decide who can drive customers’ cars, keep drives short and log each one.
Every kind of auto business
Choose yours and the quote starts with it filled in.
Guides for shop owners
Longer answers to the questions below.
Who pays when a customer’s car is damaged at your shop?9 min readGaragekeepers vs. garage liability9 min readHow to choose a deductible8 min read What to do when an employee is hurt at work10 min read
 How to read a business insurance policy10 min read
 How business income claims are calculated10 min readInsurance requirements in a commercial lease9 min readYour business insurance renewal went up. What now?9 min read
Questions from
shop owners
What insurance does an auto repair shop need?
Most shops carry garagekeepers for customers’ cars, general liability for injuries and damage to others, tools and equipment coverage for lifts and scanners, and workers’ comp once they hire. Driving customers’ cars on public roads also raises auto liability questions, which a separate policy handles.
Who pays if a customer’s car is damaged on a test drive?
Damage to the customer’s own car is usually a garagekeepers claim. Injuries to other people and damage to other cars on the road usually fall under a separate auto or garage liability policy. Check that you have both before you hand out keys.
Should I choose legal liability or direct coverage?
Legal liability pays only when your shop is at fault, like a tech backing into a post. Direct coverage pays for covered damage regardless of fault, like hail or a break-in, and costs more. Shops that keep cars overnight often choose direct coverage so customers aren’t left waiting on a fault decision.
Does garagekeepers cover damage from a bad repair?
Usually not. Damage to a car from faulty workmanship, like a part installed wrong, is commonly excluded. Injuries or damage that a faulty repair causes later may fall under liability coverage, depending on the policy.
Is the garagekeepers deductible per car?
Often, yes. Many policies apply the deductible to each car, so a hailstorm that hits ten cars can mean ten deductibles. Check your quote before you choose a deductible.
Does a detailing business need garagekeepers?
Often, yes. If customers’ cars are in your care, even for a few hours, general liability usually won’t cover damage to them. Mobile detailers should check how the policy treats cars at a customer’s address.
Do I need workers’ comp for one mechanic?
In many states, yes. Requirements depend on your state and your number of employees, and some states count part-timers. Check your state’s workers’ comp agency before your first hire starts.
Cover the cars in your bay.
Quote Garagekeepers, general liability, tools and equipment, workers’ comp and property together, and see every limit before you buy.